USPAP-COMPLIANT · INSURANCE COVERAGE
Inventory Appraisal for Insurance Purposes
Inventory appraisal services for insurance purposes covering insurable value, replacement cost, and coverage-adequacy documentation, prepared in accordance with USPAP. Accountable Inventory Appraisers values retail stock, warehouse goods, and manufacturing inventory so businesses carry the right coverage nationwide.
- Insurable value and replacement cost opinions prepared in accordance with USPAP
- Independent documentation to support your coverage limits and reduce underinsurance risk
- Scope, timing, and a fixed fee confirmed before work begins, with expedited service available
WHY IT MATTERS
Accountable Inventory Appraisers establishes the insurable value behind your inventory coverage
Your inventory is often one of the largest assets on your balance sheet, and the coverage limit on your policy is only as sound as the value behind it. Set that limit from book cost and you risk being underinsured when prices have risen; set it from retail and you may be paying premiums on value you would never recover. We prepare an independent opinion of insurable value, in accordance with USPAP, so your coverage is anchored to recognized methodology and current market evidence rather than a figure carried over from last year's books.
Many commercial property policies include a coinsurance clause that penalizes a policyholder who insures for less than a stated percentage of value, typically 80, 90, or 100 percent. If a loss occurs and your stated value falls short of that threshold, the carrier can reduce even a partial-loss payment proportionally. A current, defensible appraisal of your inventory documents that you are carrying adequate limits and gives you the evidence to support them.
Keeping an independent valuation on file also makes any future claim faster and cleaner, because the value of your stock is already documented before a loss ever happens. If you are filing a claim on inventory that has already been damaged, destroyed, or stolen, our inventory appraisal for insurance claim covers the replacement cost and actual cash value reporting your proof of loss requires. If the same inventory is pledged as loan collateral, our inventory appraisal for asset-based lending covers the net orderly liquidation value reporting lenders rely on.
What's Included
Our insurance appraisals support coverage-limit decisions, insurable value reporting, and proof-of-value documentation for your policy
Our appraisers hold credentials with leading organizations such as the ASA, ISA, AAA, and CAGA. Every report we prepare for insurance purposes follows USPAP, so it holds up under review by your carrier, broker, and underwriter.
Insurable Value Determination
We establish the insurable value of your inventory using recognized methodology and current market evidence, the figure your coverage limit should be built on.
Replacement Cost Analysis
We value what it would take to replace your stock at today's prices, so your limits reflect current market conditions rather than aging book cost.
Coverage Adequacy Review
We document that your inventory value supports your stated limits, giving you the evidence to satisfy a coinsurance clause and avoid a proportional penalty at claim time.
Defensible Reporting
Each report follows USPAP with clear methodology and market support, so the value on file holds up if your carrier or underwriter reviews it.
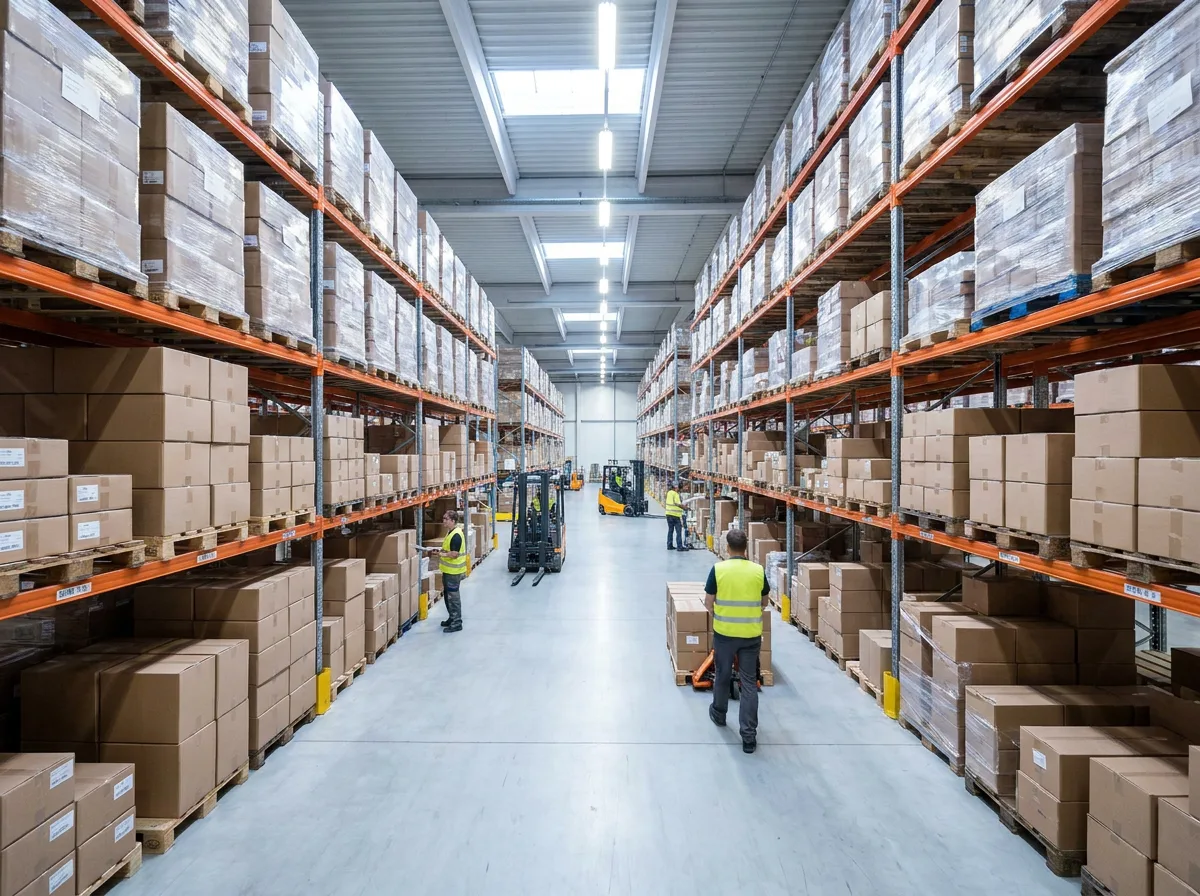
Types of Inventory
Accountable Inventory Appraisers appraises all types of insured inventory, including retail stock, warehouse goods, and raw materials
We value inventory carried across every industry for insurance coverage, from finished consumer goods to bulk industrial materials.
Retail & Consumer Stock
- Apparel and footwear
- Consumer electronics
- Furniture and home goods
- Jewelry and specialty merchandise
Warehouse & Distribution Goods
- Bulk commodities
- Palletized and bulk-stored goods
- Packaging and components
- Building materials
Manufacturing & Industrial Inventory
- Raw materials
- Work-in-process goods
- Finished goods awaiting shipment
- Equipment parts and components
Perishable & Specialty Stock
- Packaged foods and beverages
- Pharmaceuticals and medical supplies
- Seasonal and promotional inventory
- Refrigerated and frozen goods
Our Process
From coverage review to a USPAP-compliant valuation in five steps
- 01
Tell Us About Your Inventory
Share what you carry, roughly how much is on hand, and the coverage question you are trying to answer with your broker or carrier.
- 02
Records & Documentation Review
We review your inventory records, purchase history, and any existing schedules or photos to scope the valuation.
- 03
Insurable Value Analysis
Our appraiser determines insurable value and replacement cost using current market data and methodology suited to your inventory.
- 04
USPAP-Compliant Report
We prepare a report with the values and detail your broker, carrier, or underwriter needs to set and support your coverage limits.
- 05
Delivery & Support
Your report arrives on schedule, and we stay available to answer questions from you, your broker, or your carrier.
Credentials & Standards
Credentials that stand behind every insurable value we deliver
We prepare every insurance appraisal in accordance with USPAP, and our appraisers hold credentials with organizations such as the ISA, ASA, CAGA, and AAA.
International Society of Appraisers
American Society of Appraisers
Certified Appraisers Guild of America
Appraisers Association of America
Insurance Appraisal FAQ
Answers to common questions about appraising inventory for insurance purposes
What is insurable value, and how is it different from book value?
Insurable value is the cost to replace your inventory in the current market, which is what a property policy is designed to cover. Book value reflects what you paid, adjusted by your accounting method, and can sit well below or above replacement cost depending on when the goods were acquired. Setting coverage from book value is a common reason businesses end up underinsured.
Why does a business need an inventory appraisal for insurance?
An independent appraisal documents the value of your stock so your coverage limits are based on evidence rather than an estimate. It helps you avoid paying for coverage you do not need, reduces the risk of being underinsured after a price increase, and gives your broker and carrier a defensible figure to work from. It also creates a record of value before any loss occurs.
What is a coinsurance penalty, and how does an appraisal help avoid it?
Many commercial property policies require you to insure your inventory to a set percentage of its value, often 80 to 100 percent. If a covered loss happens and your stated value falls short of that threshold, the carrier can reduce your payment proportionally, even on a partial loss. A current, USPAP-compliant appraisal documents that your limits meet the requirement and supports the value you carry.
How often should inventory values be updated for insurance?
Because inventory levels and market prices change through the year, most businesses review insurable value annually or whenever the mix or volume of stock shifts significantly. Keeping a current appraisal on file means your coverage stays aligned with what you actually hold and makes any future claim faster to substantiate.
Can an inventory appraisal for insurance be completed online?
Many insurance appraisals are handled online using your inventory records, purchase documentation, and photographs, which keeps turnaround efficient. Larger or more complex inventories may warrant an on-site review. Smaller inventories are typically completed in one to two weeks and larger ones in two to four weeks, and we confirm scope, timing, and a fixed fee before we begin, with expedited service available.
Get Started
Request an Inventory Appraisal for Insurance Purposes
Tell us about your inventory and the coverage question you are working through, and we'll confirm scope, timing, and a fixed fee before we begin.